ANDREA
LANDINI.
I research quantitative finance and computational modeling, focusing on stochastic volatility models and Monte Carlo simulations, and I develop and test models using Python and C++.
Python
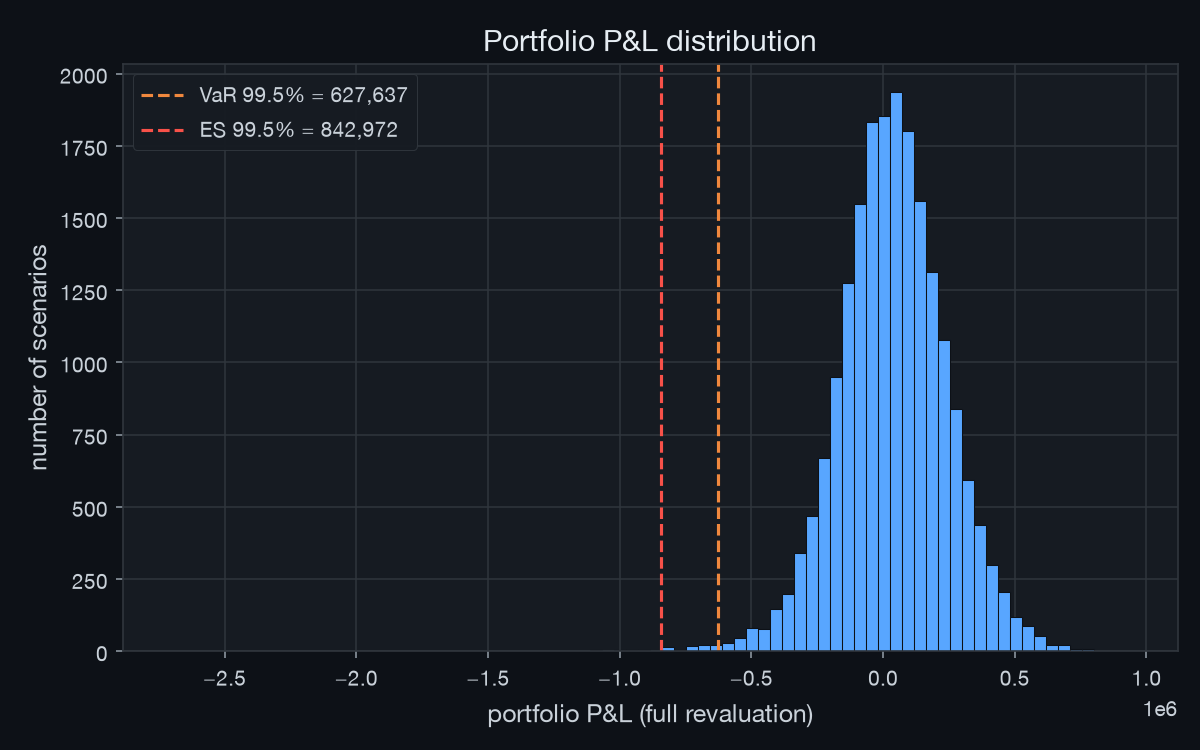
VaR engine
C++
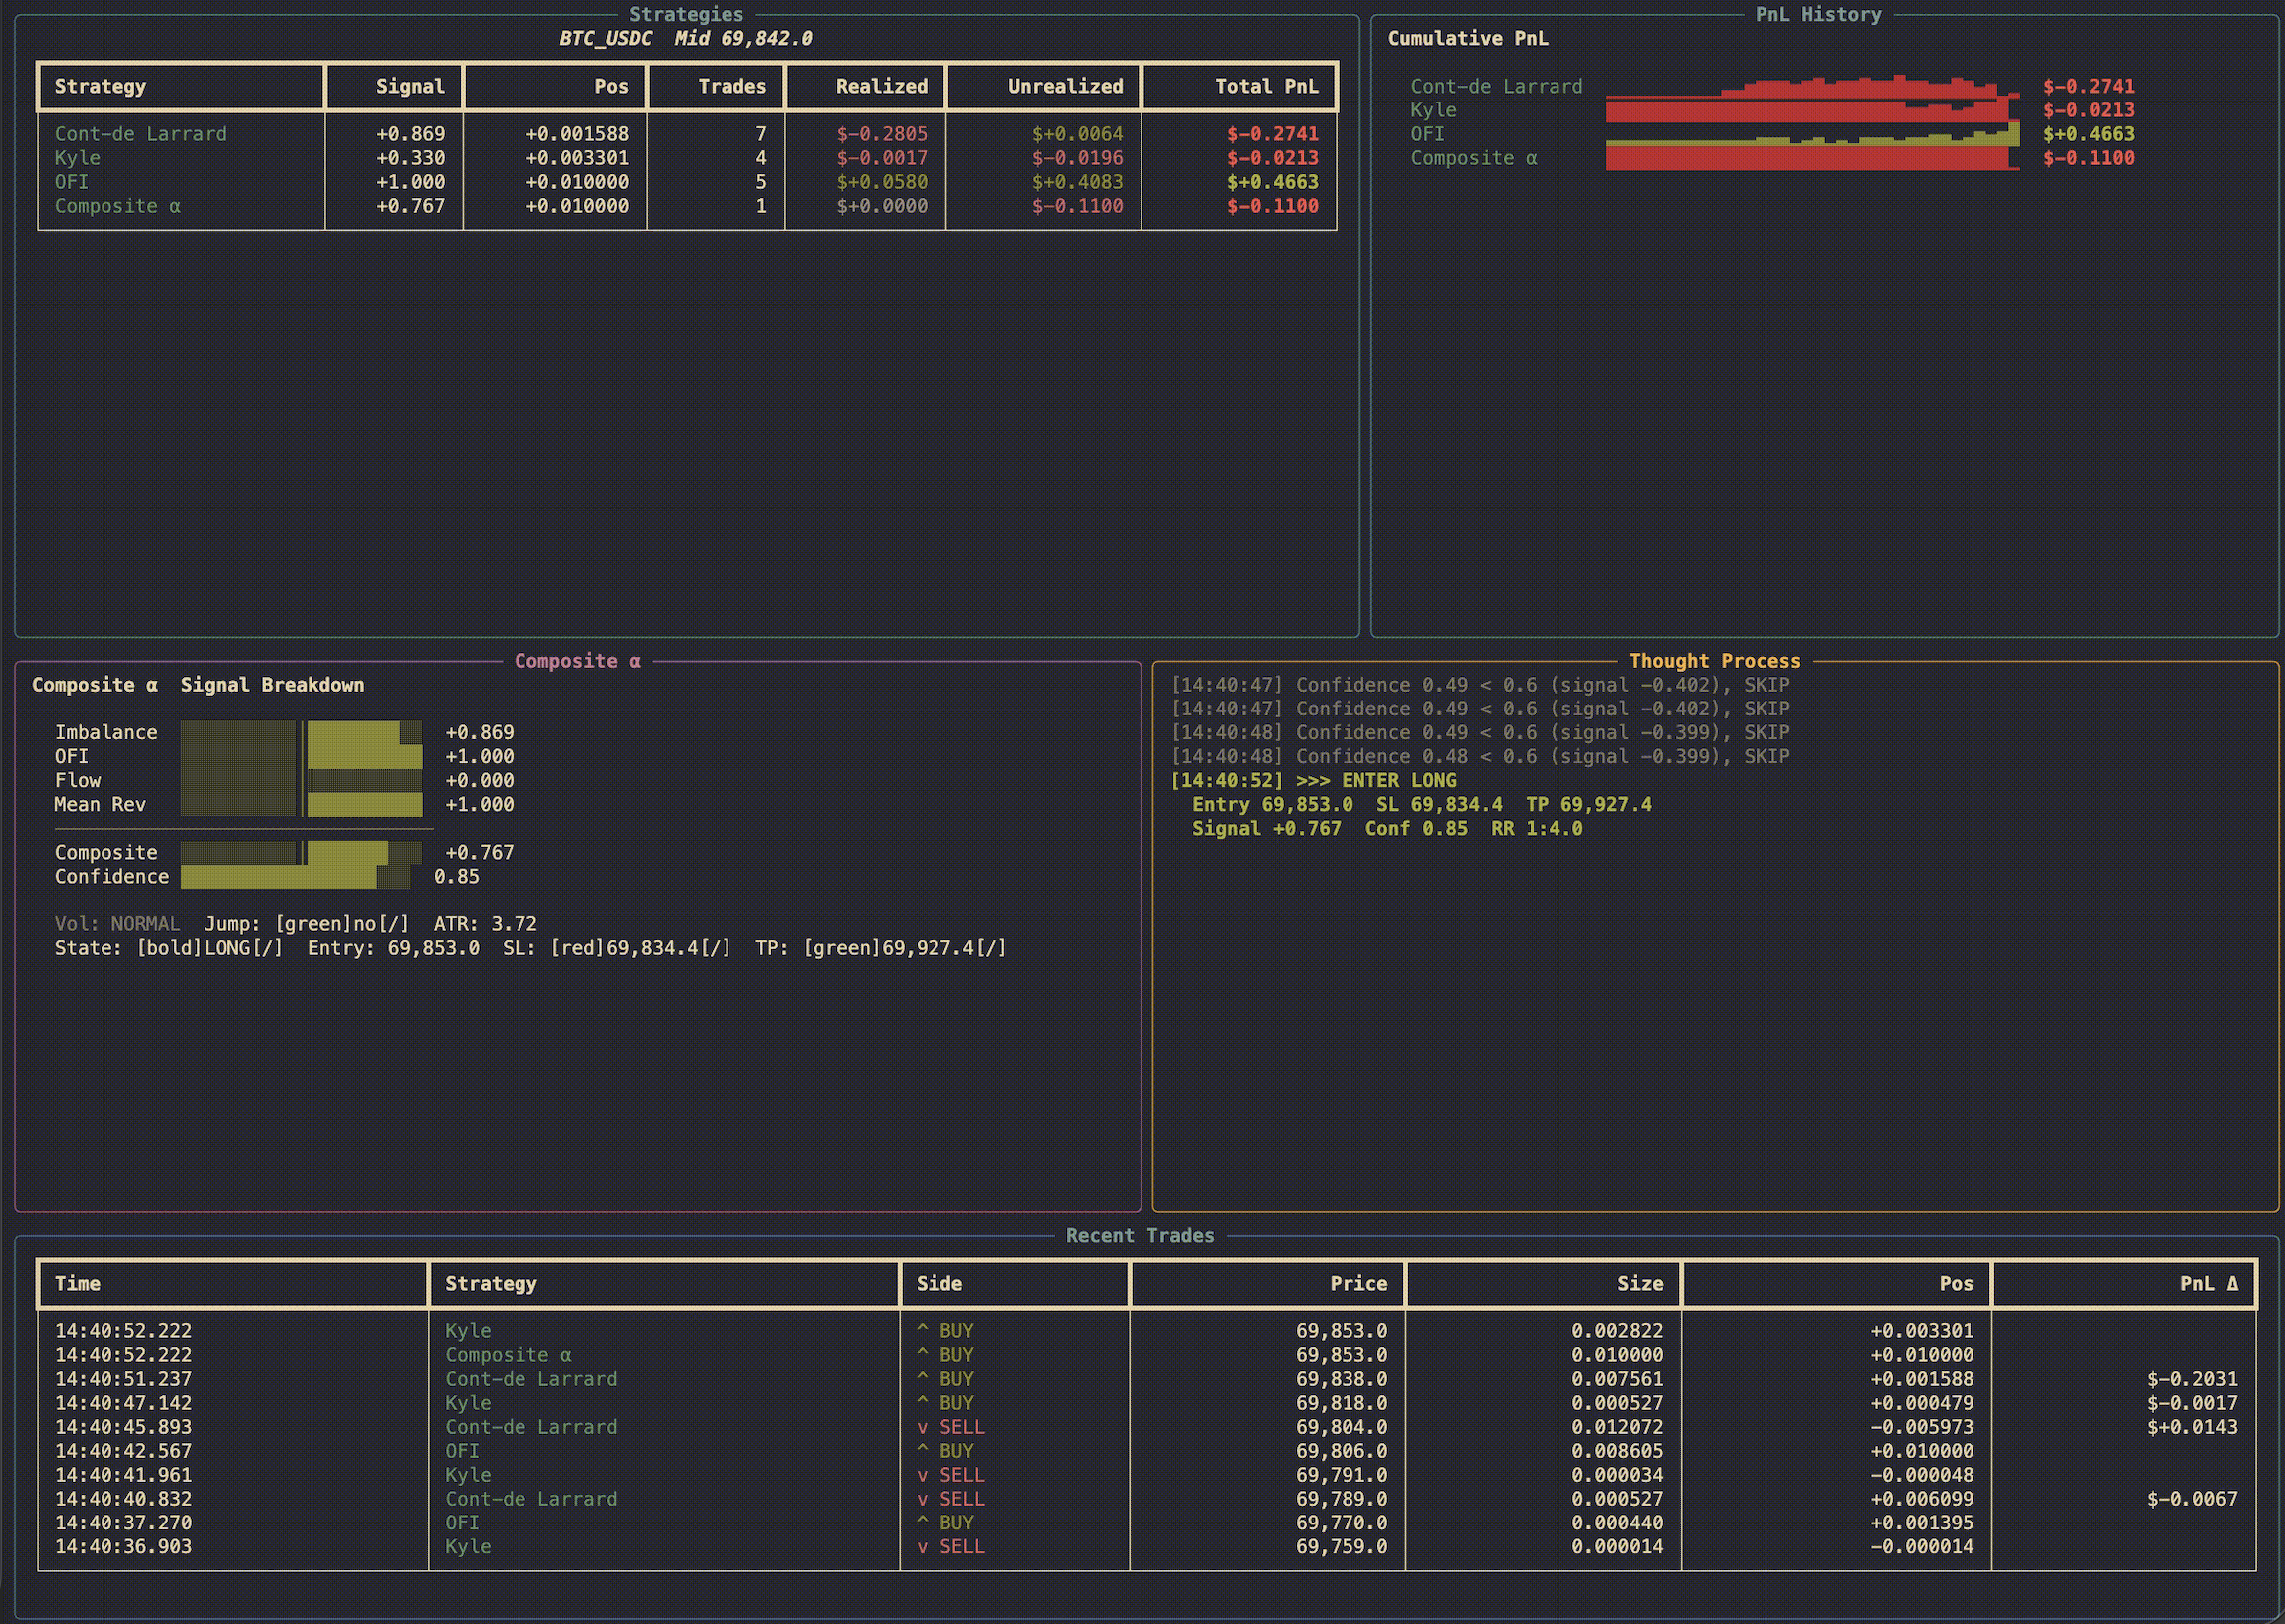
LOB strategies
From mathematical finance to production.
Theory made Code
Translating stochastic calculus into production-grade C++, robust, documented, and benchmarked.
Model Validation
Python-driven testing of pricing models against market data with statistical rigor.
Self-Built Strategies
Designing, coding, and validating strategies grounded in stochastic methods.
Models built, tested and shipped.
Market Risk
01 / 02